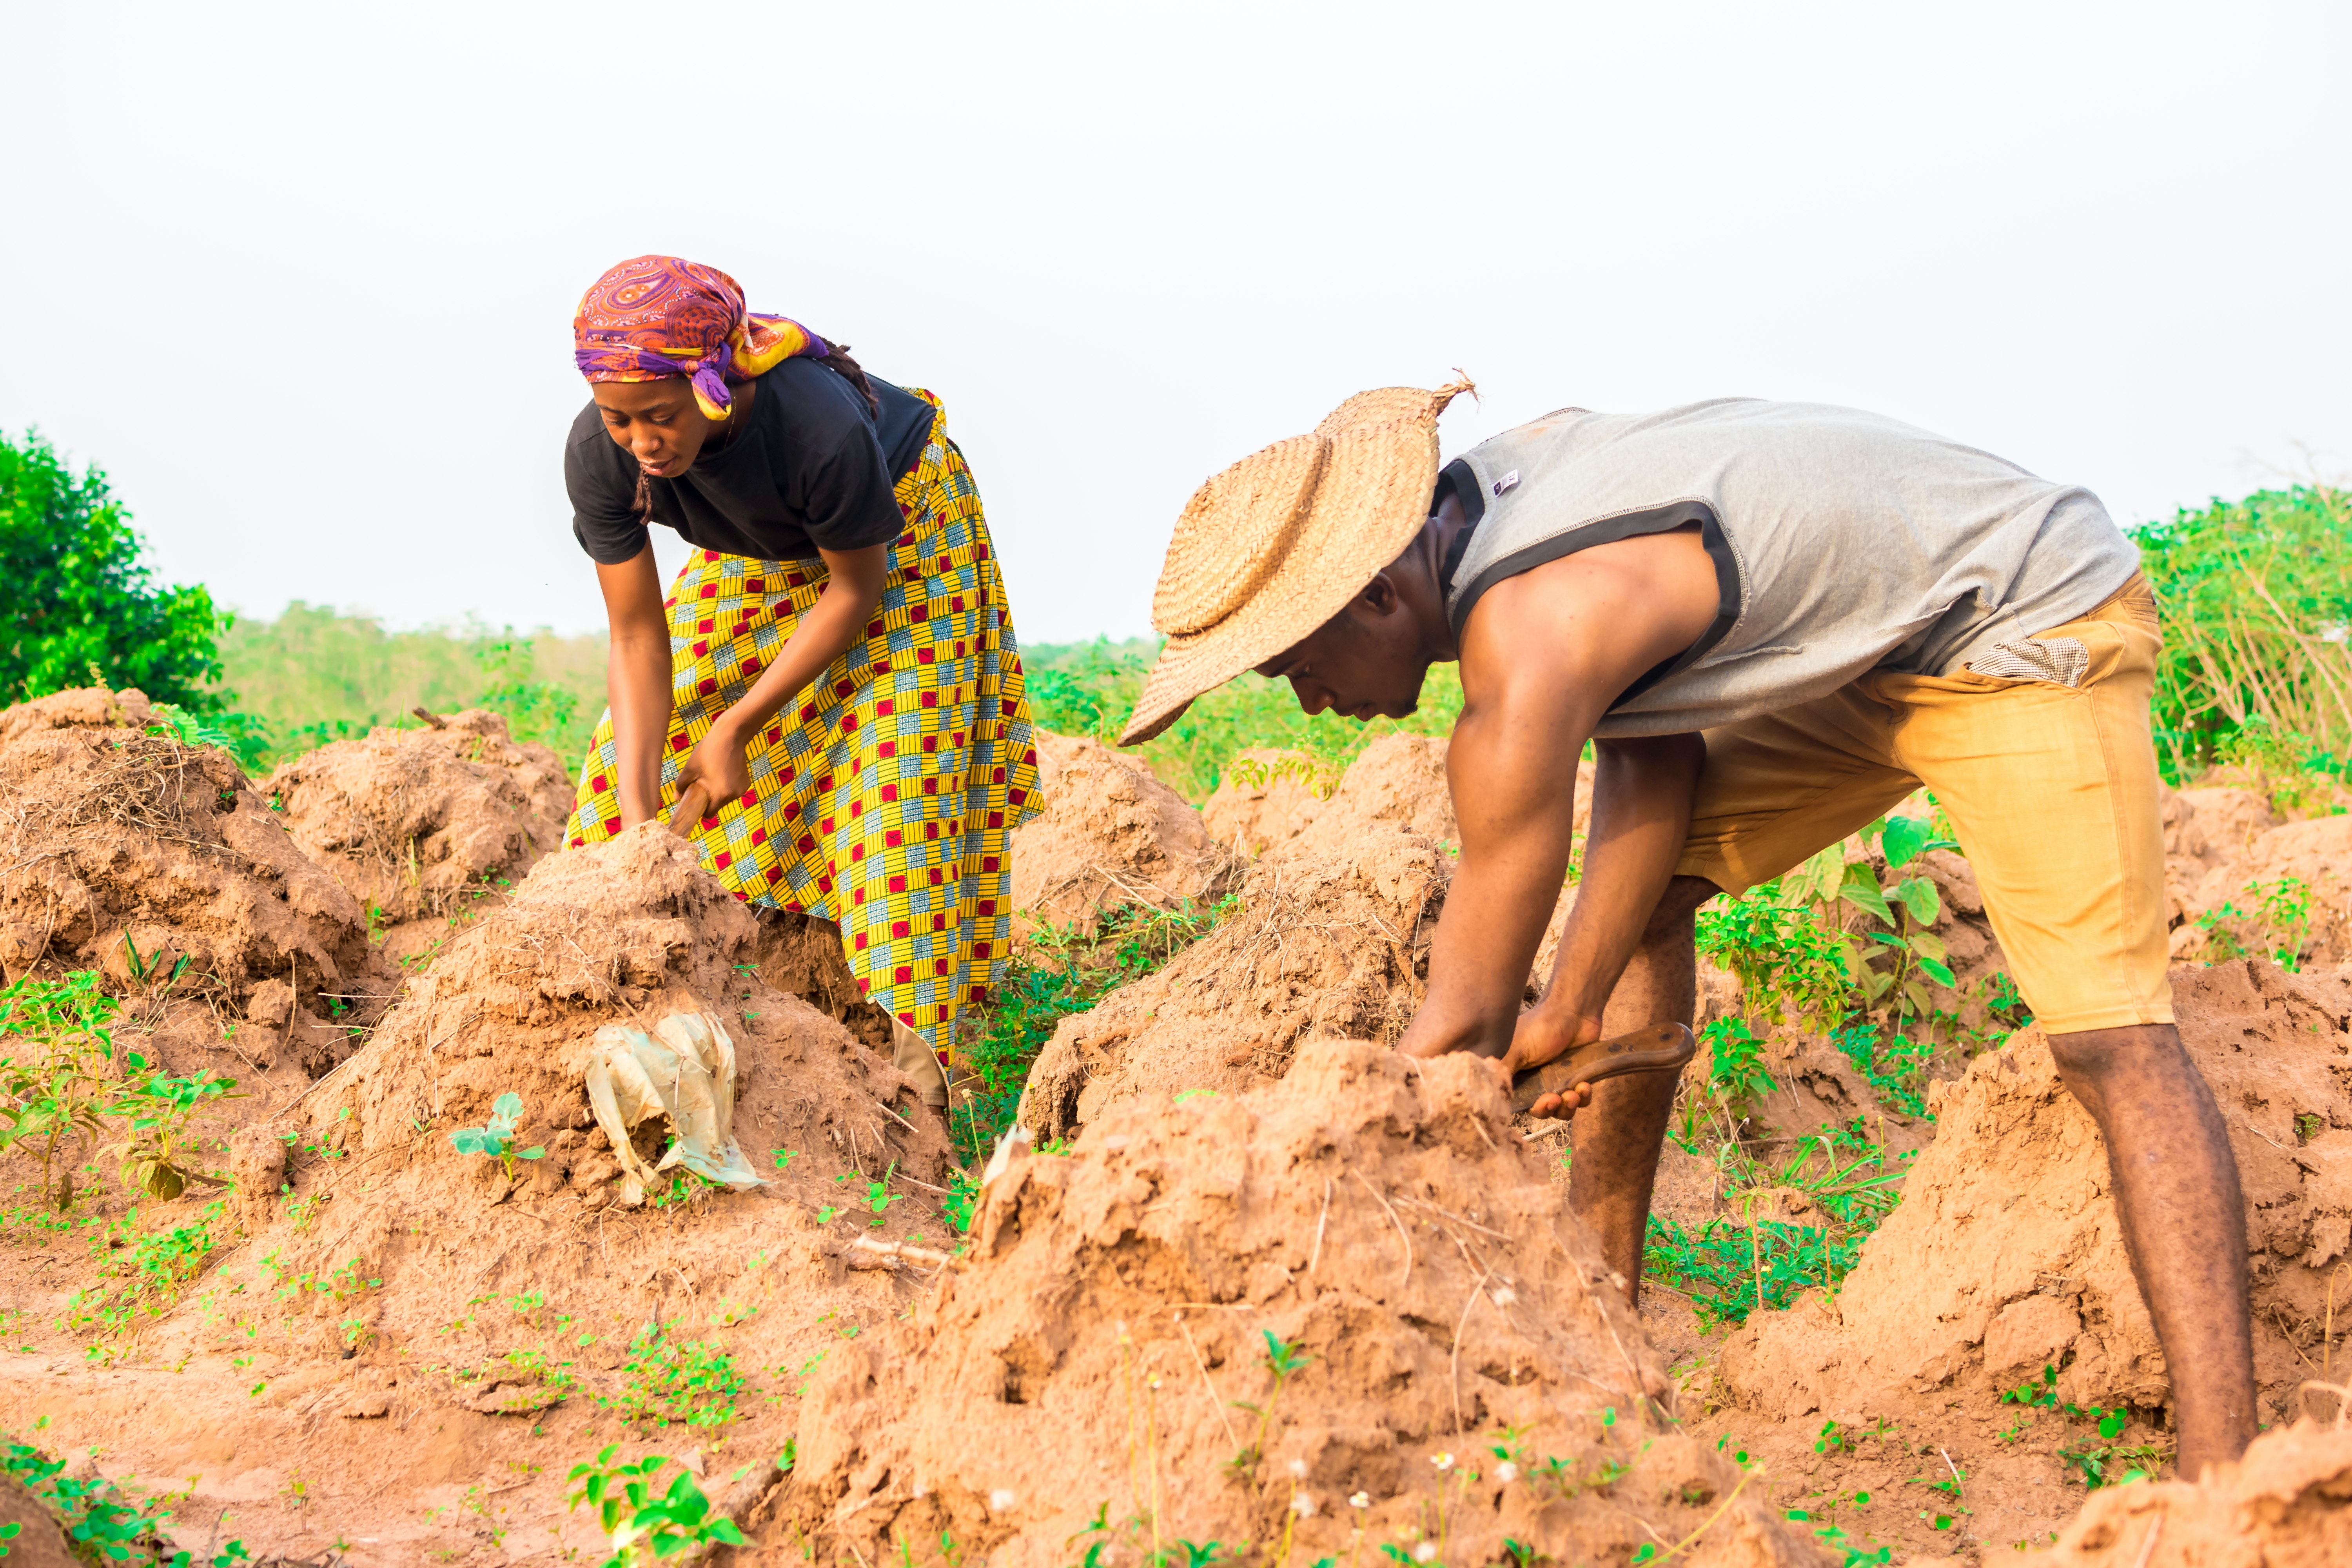
Food security for Nigeria’s 200 million people relies on small-scale farmers. Despite their importance most struggle to accumulate savings and capital, invest in economic opportunities, adopt technologies to boost production and mitigate risks and build resilience to shocks.
This points to the need to ensure that they can access and use affordable formal financial services – what’s known as financial inclusion.
A great many Nigerians don’t have access to even basic formal financial services. A government document put out in 2018 reported that just over 58% of Nigeria’s 96.4 million adults were financially included in 2016. Just under 40% were banked, 10% were served by other formal institutions and nearly 10% were served by informal service providers.
A great deal of research has been done on financial inclusion in countries across the globe. But there’s a high level of disagreement about what should be measured, and how it should be measured. One of the big gaps is that financial inclusion rankings have limited evidence on specific target groups, particularly marginalised ones.
In our paper we set out to establish what the situation was among small-scale farmers in Nigeria. Our study revisited the issue of what should be measured. Our starting premise was that owning a formal account doesn’t cut it because it doesn’t guarantee the kind of inclusion needed to ensure a safer and more secure financial future.
We adopted a multidimensional financial inclusion index for this group. The study was survey based with the aim of determining the level of financial inclusion among rural small-scale farmers in Nigeria. It was also designed to help identify areas for policy interventions.
The results indicated that 78% of rural small-scale farmers in Nigeria were financially excluded based on the broader definition. We also found that just over 27% were adequate in the access indicator – those owning formal accounts – but only 25% frequently used formal financial services. Likewise, only one-third (31%) reported not having barriers like high transaction costs, lack of identification and distance in financial participation.
Overall, we found that most rural small-scale farmers in Nigeria were least capable relative to financial well-being and participation.
Measuring financial inclusion
For the purposes of the survey we adopted the definition of smallholder households as households that had five hectares of land or fewer than 50 head of cattle or 100 goats, pigs or sheep or 1,000 chickens and where farming contributed significantly to their livelihood or consumption. There were 2,300 rural respondents in our study.
We found that having a bank account with a formal financial institution wasn’t sufficient for rural small-scale farmers in Nigeria. It still left people unable to meet some basic requirements. We considered three domains of financial inclusion.
Financial participation. This refers to the extent of access to and use of quality financial services and products such as savings, credit, insurance and payments at affordable cost. We found that there were a number of barriers to small-scale farmers achieving this. Many faced participation barriers such as high transaction costs of bank services, long distances to access services and insufficient identification to open a bank account.
Financial capability: This reflected people’s ability to effectively participate in a formal financial system through financial literacy, consumer protection and prudent financial decisions and plans. Our study found that only a few small-scale farmers met the threshold of financial literacy and consumer protection.
Financial well-being: This is also sometimes referred to as financial health. It indicates the extent of financial resilience, which includes having control over finances, or one’s financial situation. Most rural small-scale producers had control over their finance. Nevertheless, they were able only to meet their basic needs and therefore unable to save. This made it near impossible to manage economic shocks, such as the COVID-19 pandemic.
Barriers
Nigeria has adopted various innovations to ease the challenges faced in
formal financial participation.
One is the three-tiered know-your-customer regulations. The main goal is to promote flexible formal account opening and fewer restrictions on transaction operations.
Another has been the demand for a biometric bank verification number and national identification number. The idea behind this was to ease the challenges faced in financial inclusion. Both give each customer a unique identity that can be verified across formal institutions. This is expected to reduce the problem of lack of identification.
The adoption of a national financial inclusion strategy in 2012 brought a focus on consumer protection. A consumer protection framework was introduced in 2016. The goal was to promote consumer confidence, trust and fairness in formal finance institutions.
In addition, a financial literacy framework was established in 2013. The idea was to identify financial education programmes for various target groups. Financial literacy has been shown to increase the capability of consumers to successfully manage their financial plans. But our evidence suggested that these programmes are yet to reach the rural small-scale farmers. This is because it’s difficult to enrol rural populations and farmers due to distance and poor infrastructure. This increases the cost of linking up the country’s innovative programmes with agricultural operations.
Insights for policy interventions
Achieving sustainable financial inclusion in Nigeria requires interventions that strengthen financial capability, participation and well-being and not just formal account ownership.
Our results suggest financial planning products such as savings, credit and insurance plans are important for rural small-scale farmers. This is because they could help strengthen their resilience to economic shocks and crises such as the COVID-19 pandemic. This, in turn, would mean that they could continue to produce food and avert disruptions in the country’s food systems.
Planning products could also help boost their confidence to explore new economic opportunities.
In addition, affordable digital services such as mobile money could reduce barriers to financial inclusion such as high transaction costs and distant location.
Formal financial institutions also need to be more responsive to the needs of rural small-scale farmers in Nigeria.


